 16.10.2026
 4 görüntülenme
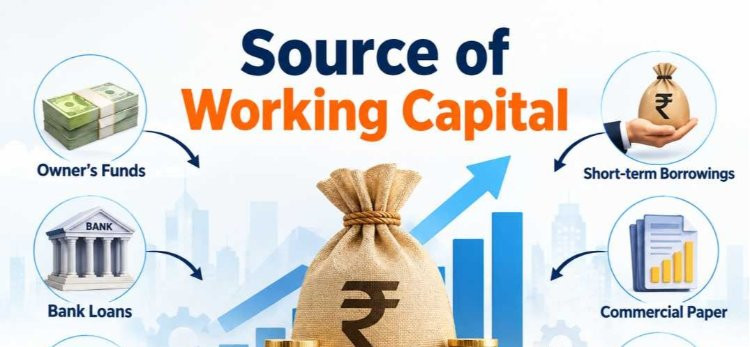
Working capital plays a vital role in the success and financial stability of any business. It enables companies to manage daily operating expenses, purchase inventory, pay employees, settle supplier invoices, and respond to unexpected financial challenges. Without sufficient working capital, even a profitable business may struggle to maintain smooth operations or take advantage of new growth opportunities.
Understanding the different sources of working capital helps business owners choose suitable funding options based on their financial requirements, cash flow patterns, and long-term objectives. Whether a company is a startup, a small enterprise, or an established organization, effective working capital management can support sustainable business success.
What Is Working Capital?
Working capital is the difference between a company's current assets and current liabilities. It measures the financial resources available to support short-term business obligations.
The formula for calculating working capital is:
Working Capital = Current Assets − Current Liabilities
Current assets generally include cash, inventory, and accounts receivable, while current liabilities include accounts payable and short-term financial obligations.
Maintaining an appropriate level of working capital helps businesses pay their expenses on time, manage financial uncertainty, and maintain operational efficiency.
Different Sources of Working Capital
1. Bank Loans for Business Operations
Business loans are a popular source of working capital for companies that need additional funds to manage operational expenses. Banks provide financing to eligible businesses for purchasing inventory, paying suppliers, managing payroll, and meeting other business requirements.
Depending on the lender and loan product, businesses may have access to different loan amounts, interest rates, repayment schedules, and security requirements.
Before applying, business owners should compare the total borrowing cost, processing fees, repayment terms, and eligibility criteria to ensure that the financing fits their financial position.
2. Invoice Discounting for Faster Cash Flow
Invoice discounting is a financing option that allows businesses to access funds against eligible unpaid customer invoices. It can help companies reduce the impact of delayed payments and maintain sufficient liquidity for daily operations.
For example, a business that supplies products to customers on credit may have to wait several weeks or months to receive payment. Invoice discounting can provide access to a portion of the invoice value earlier, subject to the provider's terms.
This source of working capital is particularly useful for businesses with regular sales but lengthy customer payment cycles. Companies should evaluate financing charges, eligibility conditions, and repayment obligations before selecting a provider.
3. Trade Credit from Suppliers
Trade credit allows businesses to purchase goods or services and pay suppliers at an agreed later date. This arrangement helps companies obtain the inventory or materials they need without making immediate payments.
For example, a wholesaler may receive goods with a 30-day payment period and use that time to sell the products before paying the supplier.
Trade credit can improve cash flow and reduce the immediate need for external borrowing. Maintaining a good payment history and strong supplier relationships may also help businesses negotiate better credit terms.
4. Bank Overdraft Facilities
A bank overdraft is a short-term credit facility that allows an eligible business to withdraw funds beyond its available account balance, up to an approved limit.
Businesses can use overdrafts to manage temporary cash shortages, cover urgent expenses, and address gaps caused by delayed customer payments.
Interest is generally charged on the amount used, according to the lender's terms. Business owners should monitor overdraft usage carefully and avoid depending on it continuously for long-term financial needs.
5. Retained Earnings and Business Profits
Retained earnings are profits that a company keeps within the business rather than distributing to its owners or shareholders. These funds can be used to finance inventory purchases, operating expenses, and other business requirements.
Using retained earnings can reduce the need for borrowing and help businesses avoid additional interest costs. However, companies should maintain adequate cash reserves for emergencies and future investments.
This option is especially valuable for businesses that generate consistent profits and want to grow while limiting their dependence on external financing.
6. Short-Term Business Financing
Short-term financing helps businesses cover immediate financial requirements over a defined repayment period. It may be used for seasonal inventory purchases, urgent supplier payments, temporary operating expenses, or short-term cash flow gaps.
Such financing can be helpful when a company expects sufficient cash inflows to meet upcoming repayments. However, business owners should carefully assess repayment frequency, interest rates, additional fees, and the impact on future cash flow.
7. Financing from NBFCs and Other Financial Institutions
Non-banking financial companies (NBFCs) and other financial institutions may offer working capital loans and other financing products to eligible businesses.
These providers can give businesses additional options beyond traditional bank lending. Depending on the product, funding may be structured around business turnover, creditworthiness, outstanding invoices, or other eligibility factors.
Before choosing a lender, businesses should verify its credibility, compare the total cost of financing, and review all contractual conditions.
8. Equity Investment from Business Owners or Investors
Businesses may also strengthen their working capital through additional contributions from owners or investments from external investors.
Owner contributions can provide funds without creating conventional loan repayment obligations. External equity investment may also bring strategic guidance and business connections, depending on the investor.
However, external investment can involve sharing ownership, profits, and decision-making authority. Businesses should consider these implications before choosing equity financing.
How to Choose the Best Source of Working Capital
Selecting the right source of working capital requires a clear understanding of business needs and financial capacity.
Assess Your Cash Flow Requirements
Calculate how much funding is needed to cover operating expenses, inventory purchases, payroll, and supplier payments. Identify whether the requirement is temporary, seasonal, or ongoing.
Compare Financing Costs
Review interest rates, processing charges, service fees, repayment schedules, and the total amount payable. A financing option with a lower advertised rate may still be expensive if it includes substantial additional fees.
Evaluate Repayment Capacity
Estimate future cash inflows and ensure that the business can meet repayment obligations without affecting essential expenses. Avoid taking on more debt than the business can reasonably manage.
Consider Funding Availability
Some financing options may require extensive documentation or approval procedures. Consider the urgency of the funding requirement and the expected time needed to obtain the funds.
Match Financing with Business Needs
Short-term cash flow gaps may be addressed through invoice discounting or overdrafts, while retained earnings and suitable loans may support broader operational requirements. The right choice depends on the business's circumstances and the financing terms available.
Benefits of Effective Working Capital Management
Smooth Business Operations
Adequate working capital helps businesses pay employees, purchase inventory, and meet supplier obligations without unnecessary disruption.
Improved Cash Flow
A well-planned financing strategy helps companies manage delayed payments and maintain sufficient funds for regular expenses.
Stronger Supplier Relationships
Making payments on time can improve supplier confidence and create opportunities to negotiate favourable purchasing terms.
Better Growth Opportunities
Access to appropriate working capital allows businesses to respond to increased demand, expand product offerings, and explore new markets.
Reduced Financial Pressure
Monitoring working capital regularly can help businesses identify cash shortages early, manage borrowing requirements, and prepare for unexpected expenses.
Common Working Capital Management Mistakes to Avoid
Businesses should avoid relying entirely on borrowed funds, maintaining excessive inventory, allowing customer invoices to remain overdue, and failing to forecast upcoming expenses.
Another common mistake is using short-term financing for investments that require several years to generate returns. A mismatch between repayment schedules and cash inflows can place unnecessary pressure on the business.
Regular reviews of inventory, accounts receivable, accounts payable, and cash flow forecasts can help business owners make informed financing decisions.
Conclusion
Exploring different sources of working capital is essential for maintaining financial stability and achieving business success. Bank loans, invoice discounting, trade credit, overdraft facilities, retained earnings, short-term financing, NBFC funding, and equity contributions each offer different advantages depending on a company's financial requirements.
The best source of working capital depends on the business's cash flow cycle, funding needs, repayment capacity, and long-term objectives. By comparing available options, controlling expenses, collecting customer payments efficiently, and planning finances carefully, businesses can improve liquidity and build a strong foundation for sustainable growth.
Frequently Asked Questions
What are the different sources of working capital?
Common sources include bank loans, invoice discounting, trade credit, overdraft facilities, retained earnings, short-term financing, NBFC loans, and equity contributions.
Which source of working capital is suitable for small businesses?
Small businesses may consider supplier credit, retained earnings, invoice discounting, or business loans, depending on their eligibility, cash flow requirements, and repayment capacity.
How does invoice discounting support business success?
Invoice discounting allows businesses to access funds against eligible unpaid invoices, helping them manage operating expenses and reduce the effect of delayed customer payments.
Why is working capital important for business growth?
Working capital supports daily operations, inventory purchases, supplier payments, and payroll. Adequate liquidity also helps businesses respond to new opportunities and unexpected expenses.
How can a business improve its working capital?
A business can improve working capital by collecting receivables faster, managing inventory efficiently, negotiating suitable supplier payment terms, controlling expenses, and choosing appropriate financing options.
Yorumlar (0)
Bu gönderi için henüz bir yorum yapılmamış.
Yorum Bırakın